Deducting workers' accommodation from tax – what companies need to know
· 7 min read · Gnann Verwaltung GmbH
In short: For the business, the cost of accommodating fitters on off-site assignments (Auswärtstätigkeit) is a deductible business expense (Betriebsausgabe), and it can be reimbursed to employees tax-free. In Germany, short-term accommodation is subject to the reduced VAT rate (Umsatzsteuer) of 7%, which companies can reclaim as input tax (Vorsteuer) with a proper invoice. After 48 months at the same work location, accommodation costs are capped at €1,000 per month.
Please note: This guide gives a general overview (as of September 2026) and is no substitute for tax advice. Please check individual cases with your tax adviser (Steuerberater).
Why this matters for companies
If you send fitters, service technicians or entire installation crews to Augsburg, accommodation quickly adds up to four-figure sums per project. An example using our prices: four fitters in a shared room for 30 nights cost from 4 × 30 × €15 = €1,800. Whether these costs reduce your taxable profit, whether you get the VAT back and whether your workers have to pay tax on the reimbursement depends on a few important rules.
1. Accommodation costs are business expenses
If an employee stays overnight away from home and away from their regular place of work (erste Tätigkeitsstätte) for work reasons, this counts as an off-site assignment (Auswärtstätigkeit) – typical for fitters working on changing construction sites. The cost of the workers' room or workers' apartment is then a business expense (Betriebsausgabe) for the company and reduces its profit. The same applies if the owner of a trade business is out on an installation job themselves.
What matters is that the stay is work-related (berufliche Veranlassung). This should be clear from your records: the order or project, the work location, the period and the names of the workers accommodated. The easiest way is to have these details – for example a project or cost centre number – printed on the landlord's invoice.
2. Tax-free reimbursement to employees
If employees pay for the accommodation themselves and claim it back, the employer can reimburse the actual accommodation costs tax-free under Section 3 No. 16 of the German Income Tax Act (§ 3 Nr. 16 EStG). Alternatively, the tax authorities allow a flat rate of €20 per night for overnight stays within Germany without individual receipts – but the stay must actually have taken place and must not have been provided by the employer.
For companies, booking directly is almost always more practical: the business books and pays for the workers' room itself, and the invoice is made out to the business. There is then no reimbursement process for the employee, and the business keeps the input tax deduction (Vorsteuerabzug) in its own hands.
3. VAT: 7% and input tax deduction
The short-term letting of living and sleeping rooms for accommodation is subject to the reduced rate of 7% (§ 12 Abs. 2 Nr. 11 UStG, the German VAT Act). If the landlord is liable for VAT and shows it on the invoice, a company entitled to deduct input tax can claim it back as input tax (Vorsteuer).
Two points are often overlooked in practice:
- Ancillary services such as breakfast or parking are not part of the favoured accommodation service and are taxed at the standard rate of 19%. They should therefore be listed separately on the invoice. At Monteurzimmer Augsburg, parking at the house is free, and thanks to their own kitchen, teams cater for themselves.
- Long-term letting (usually from six months) may be VAT-exempt as residential letting. In that case there is no input tax to reclaim either. The invoice shows which applies.
4. What the invoice must include
To deduct input tax, the company needs a proper invoice under § 14 Abs. 4 UStG. Check the following details:
| Mandatory detail | Example / note |
|---|---|
| Landlord's name and address | e.g. Gnann Verwaltung GmbH, Barfüßerstraße 7, 86150 Augsburg |
| Your company's name and address | full company name, not the fitter's private address |
| Landlord's tax number (Steuernummer) or VAT ID (USt-IdNr.) | |
| Invoice date and sequential invoice number | |
| Type and scope of the service | e.g. "Overnight stay, shared room, 4 persons, 30 nights" |
| Service period | arrival and departure dates |
| Net amount, tax rate and tax amount | split into 7% and, where applicable, 19% |
For small invoices up to €250 gross (Kleinbetragsrechnung), fewer details are required (including the landlord, the service, the gross amount and the tax rate). For longer stays this is rarely relevant.
E-invoicing: Since 2025, businesses in Germany must be able to receive e-invoices (E-Rechnung); the obligation to issue them is being phased in with transition periods until 2028. Check with your accounts department which format you need and mention it when booking.
5. Meal allowances: the kitchen saves money
In addition to accommodation, employers can pay meal allowances (Verpflegungspauschalen) tax-free for off-site assignments: €14 for days with more than 8 hours' absence and for arrival and departure days, and €28 for full 24-hour days (rates for Germany – please check the current figures). At the same work location, the allowances apply only for the first three months.
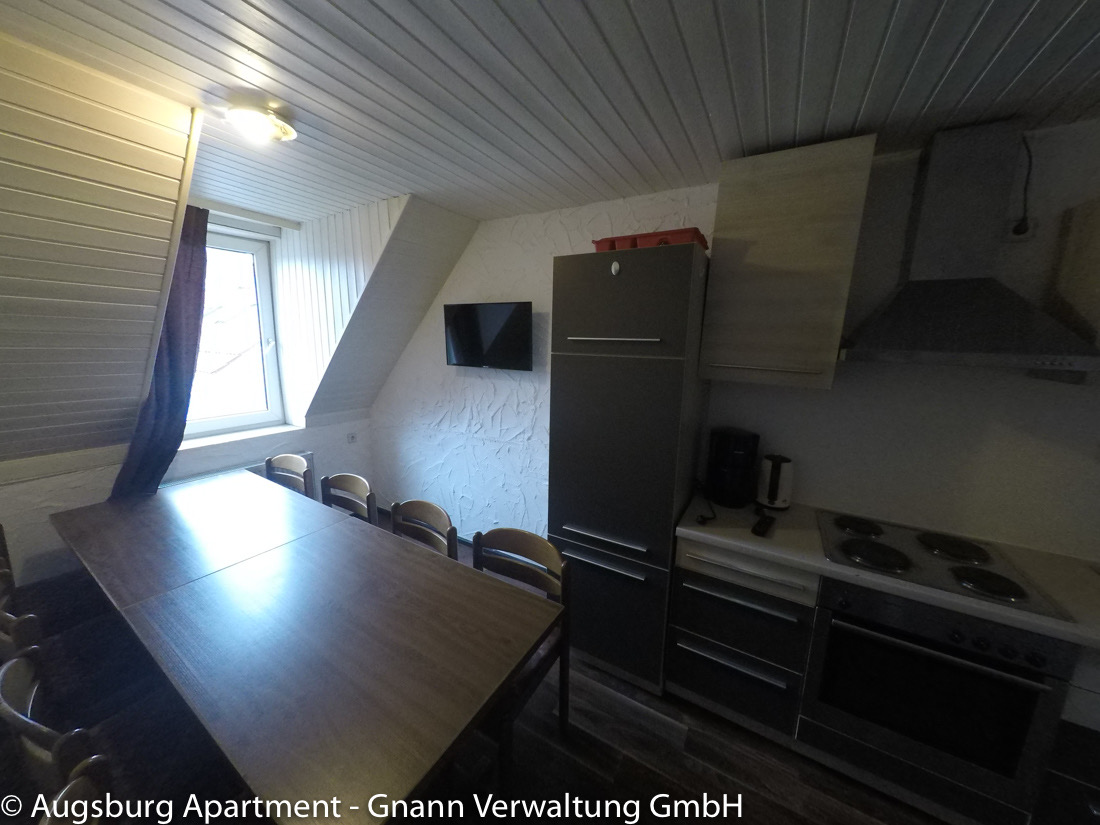
Because each of our workers' rooms comes with a fully equipped kitchen, teams can cook for themselves. This lowers actual food costs – and employees are still entitled to the allowance as long as the employer does not provide meals.
6. The 48-month limit for long-term projects
If an off-site assignment at the same place of work lasts longer than 48 months, accommodation costs after that point can only be taken into account for tax purposes up to €1,000 per month (§ 9 Abs. 1 Satz 3 Nr. 5a EStG). Breaks of at least six months restart the clock. For most installation projects this limit does not matter, but it can for major construction sites or long-term maintenance contracts.
For comparison: even our largest unit – the 16-person house from €200 per day – works out at around €375 per person per month, well below this limit.
7. Special case: double household
If Augsburg becomes an employee's regular place of work (erste Tätigkeitsstätte), for example after a longer-term transfer, and they keep their main residence elsewhere, it is no longer an off-site assignment but a double household (doppelte Haushaltsführung). Accommodation costs of up to €1,000 per month are still deductible or can be reimbursed tax-free, but separate conditions apply. It is particularly worth checking this with your tax adviser.
Checklist for your accounts department
- Book directly in the company's name, not the employee's
- Provide the billing address and project or cost centre number when you enquire
- Document the names of the workers accommodated and the service period
- Check the invoice for the mandatory details and separate tax rates
- Record meal allowances and the three-month limit in your travel expense process
- For projects lasting several years: keep an eye on the 48-month limit
Book workers' accommodation in Augsburg for your company
At Monteurzimmer Augsburg you book directly with Gnann Verwaltung GmbH – no booking portal and no agency fees. Include your company name and billing details in your enquiry. Our range goes from workers' rooms from €12 per person per night and the workers' apartment for up to 20 people to the workers' house. How to prepare the booking on the organisational side is explained in our checklist for installation teams.
Frequently asked questions about tax deductions
Can a company deduct workers' accommodation from its taxes?
Which VAT rate applies to workers' rooms?
Does the fitter have to pay tax on the reimbursement?
Is there a flat rate for overnight stays?
What is the 48-month rule?
Request accommodation for your team in Augsburg
Workers' rooms from €12 per person per night, apartments and houses for up to 20 people – booked directly with Gnann Verwaltung GmbH.
More guides
- Checklist: booking accommodation for installation teams in Augsburg
From planning to departure: 23 points that dispatchers and site managers should keep in mind when booking workers' accommodation in Augsburg.
- Long-term accommodation for tradespeople: workers' room or workers' apartment?
Who is best served by a single or multi-bed room, and when is the whole apartment worth it? A comparison with real prices and worked examples for teams of 2 to 16 people.
- Parking in Augsburg – tips for tradespeople and fitters with a company vehicle
Which parking rules apply to vans and trailers, how to get a no-stopping zone (Halteverbot) in front of the site and what to look for in your accommodation.
- DIY Stores, Tool Hire and Workwear in Augsburg – A Shopping Guide for Workers
DIY store, trade wholesaler or plant hire? Which source suits which need, what applies on Sundays and how to plan your materials shopping during the working week.
- Laundry, Shopping, After Work: An Everyday Guide for Workers in Augsburg
Washing machine, kitchen, shop opening hours and time off: how workers organise everyday life in Augsburg – with an example calculation for self-catering.
- Gyms, Swimming Pools and Sport for Workers in Augsburg
What helps against back and shoulder pain from working on site, and where workers in Augsburg can train, swim and run.